
A 5- to 7-year-old doesn’t need to know how to calculate interest to start learning how to handle money. At this age, what matters is understanding that choices have a cost, money runs out, and waiting is a skill, too. Financial education for children ages 5 to 7 works best when it moves beyond talk and becomes part of everyday life: short conversations, real examples, play, and repetition.
This guide shows you how to teach young children about money without turning your home into a classroom. You’ll learn what they already understand, when an allowance makes sense, which games really help, and which common mistakes can confuse more than they teach. If your question got mixed up with terms like physical education admissions cutoff score or admissions cutoff score for physical education, note that those are separate topics—this guide focuses on building habits at a child’s own pace.

The Essentials
- Children ages 5 to 7 already understand exchanging, choosing, and waiting; these are the building blocks for understanding the value of money.
- An allowance can work at this age if it’s small, predictable, and tied to simple choices—not control or punishment.
- Play-based shopping, piggy banks, and “choose between two items” activities teach more than long explanations.
- Adults’ example matters more than anything they say: financial habits at home teach without a lecture.
- Money should be a topic of conversation for young children, not a source of anxiety, guilt, or threats.
What Children Ages 5 to 7 Can Already Understand About Money
In practice, children in this age group already understand that money is used to trade for things, that it isn’t unlimited, and that choosing one item may mean giving up another. That’s the heart of early childhood financial education at this age: recognizing value, priorities, and the need to wait before learning more complex math.
Between ages 5 and 7, children still think in concrete terms. They learn by seeing, touching, and comparing. If you say, “That costs money,” without showing what that means in practice, they’ll forget it quickly. But if they watch you choose between getting ice cream today and saving for something else, the idea starts to take shape.
What They Can Learn at This Age
- Understand that everything has a price.
- See that buying something now may mean not being able to buy something else later.
- Recognize that saving money is a way to wait for something bigger.
- Tell the difference between wants and needs in simple situations.
For a young child, the value of money doesn’t come from the number on a bill, but from the firsthand experience of trading, waiting, and choosing.
If you want a broader foundation for managing your household finances and setting a good example, revisit principles of behavior and routine in financial habits that strengthen everyday decisions. Young children learn more from consistency than from lectures.
How to Teach the Value of Money Through Short Conversations and Simple Language
Teaching young children about money takes short sentences and visible examples. Instead of explaining “budget,” say, “We can’t get both today; we need to choose one.” Instead of saying “expense,” say, “That uses some of the money we have.” Children understand when your words match what’s happening in real life.
Phrases That Work Better Than Long Explanations
- “We have money set aside for this.”
- “If you choose this, the other thing will have to wait.”
- “Let’s see how much more we need.”
- “Saving is a choice, too.”
Anyone who works with children knows that most confusion doesn’t come from a lack of intelligence; it comes from adults making things too abstract. At this age, talking about money means talking about familiar situations: the grocery store, a toy, a snack, or an outing. When children see the link between a decision and its consequences, they learn.
A useful starting point for adults is to separate emotions from decisions. This comes up often in behavioral economics applied to everyday financial decisions, because money is rarely just about math; it’s also about habits, impulse, and repetition. That’s even clearer with young children.
Allowance at This Age: When to Start and How to Begin

An allowance can make sense for children ages 5 to 7, but it’s not a requirement. It works best as a way to practice waiting, making choices, and following simple agreements. If your child still has trouble handling minor disappointments without disrupting the routine, it may be too soon to expect regular financial independence.
How to Start Without Overcomplicating It
- Set a small, fixed amount.
- Give it on a predictable day, such as Saturday or Sunday.
- Explain the rule in one sentence: “This money is for practicing how to make choices.”
- Don’t use the allowance as punishment or as a reward for basic behavior.
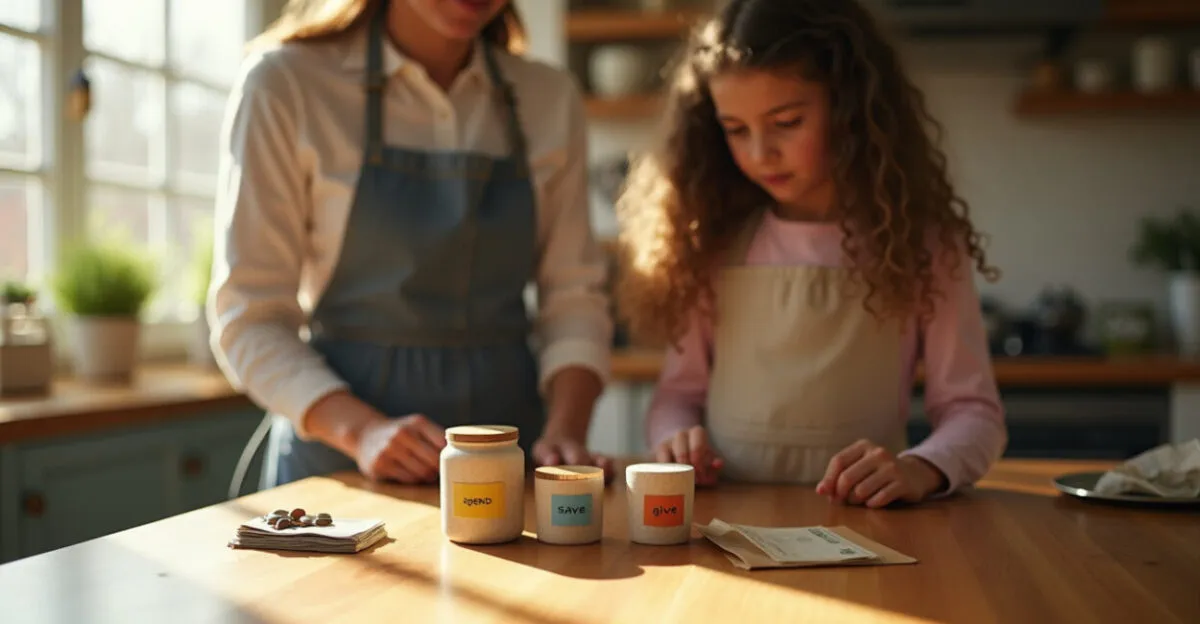
- If possible, set up three jars: spend, save, and give.
This approach works well when the family can stick with it, but it falls apart when it turns into a weekly negotiation. If the amount changes based on mood, fatigue, or guilt, the child learns inconsistency, not organization. Experts disagree on whether children should get an allowance this young; I see it as more useful for building habits than for fostering independence at this age.
The difference between an educational allowance and a confusing one comes down to whether adults stick to the rules without turning money into a reward, threat, or bargaining chip.
If your household needs to get the basics organized, it can help to revisit a simple tracking system in a five-step monthly budget. Your child won’t be reading a spreadsheet, but they’ll notice when adults have routines and plans they can count on.
Read also: Behavioral Economics Applied to Everyday Financial Decisions
Games and Activities That Teach Choices, Trading, and Priorities
Financial education games work because they take the pressure off and make ideas part of the experience. Young children learn best when they compare objects, choose from a limited set of options, and see immediate results. Games with coins, cards, piggy banks, and pretend stores teach more than a lecture about “responsibility.”
Activities Worth Trying
- Pretend store: The child “buys” toys with play money and has to make choices.
- “Now or later” box: Two things they want—one for today and one to save for.
- Piggy bank challenge: Save for a few days to reach a small goal.
- Grocery store at home: Compare prices and decide what “fits” within the play budget.
A mom shared that her son wanted every treat at the grocery store. Instead of arguing, she started giving him three play coins and saying, “You can choose just one.” At first, he cried. Later, he started looking at prices, thinking it over, and even saying, “We can’t get that today.” It may seem like a small change, but it’s a big step for a child this age.
Read also: Financial Education for Teens: A Complete Guide to Building a Secure Future
If you like using structured activities to reinforce behavior, you can pair them with content on tools for making better decisions. The principle is the same: make abstract ideas concrete and choices visible.
Everyday Habits That Reinforce Financial Education at Home
Financial education for children ages 5 to 7 comes less from a single conversation and more from repeated routines. Saving coins, comparing two products, waiting a day before buying something, and helping with the shopping list are simple habits that build an understanding of value without pushing children to grow up too fast.
Habits That Teach Without a Lecture
- Take your child along to compare prices in simple situations.
- Let them add one item they’ve chosen to the grocery list.
- Say out loud when something isn’t part of the plan.
- Show that saving some money is part of the routine.
Adults’ example matters, too. If the household is always making impulse purchases, children notice before they understand the word “planning.” Anyone who has organized their own finances knows how much routines can reduce anxiety; a good place to start is how to organize your personal finances from scratch. Children don’t need to see the numbers, but they do need to see consistency.
Another valuable habit is not turning every choice into a purchase. A trip to the park, a library visit, cooking together, and fixing a toy can also teach children about cost, care, and priorities. This helps them understand that buying something isn’t always the answer.
What to Avoid So You Don’t Confuse or Pressure Your Child
The biggest mistake is using money to scare children. A 5- to 7-year-old shouldn’t hear things like “We never have any money,” “Money is a problem,” or “If you spend it, it’ll all be gone.” These phrases can create anxiety and teach emotional scarcity instead of the value of money.
Common Mistakes
- Talking about money with scolding or guilt.
- Using an allowance as punishment for ordinary behavior.
- Giving in and promising a purchase just to stop the child from asking.
- Expecting the child to “understand” like an adult.
There’s also no need to overdo lessons on investing, interest, or passive income. Those topics can wait. At this age, the priority is building a foundation: making choices, waiting, comparing, handling manageable frustration, and understanding limits. The rest can come later, with more maturity and context.
One important caveat: this approach works best when adults have at least some stability. If the family is facing real financial hardship, it’s better to shield the child from the weight of those problems and explain only what’s necessary. Honesty helps; placing your worries on their shoulders doesn’t.
Practical Examples You Can Try Today Without Changing Your Routine
The quickest way to start is to use situations that already come up. At breakfast, show the difference between bringing a piece of fruit and choosing a pricier snack. At the grocery store, ask your child to choose between two items within a small limit. At the end of the week, use the piggy bank to count coins and talk about waiting.
Three Things to Try Right Away
- At the store: “We have money for one extra item today.”
- For a toy: “Let’s save half and see when we have enough.”
- On an outing: “You choose: ice cream now or a toy later.”
If your child already takes part in sports, school, or a community program, everyday routines offer even more opportunities to compare effort, time, and rewards—without making everything about financial merit. And if you’re looking for a different way to organize family life, remember to distinguish basic education from long-term planning; they’re different layers.
Here’s the main point: teaching children about money at this age isn’t about talking about wealth; it’s about teaching them to live with limits. When children learn this early, they enter their teen years with fewer impulses and more tools to make good decisions.
Next Steps
Choose just one practice to try this week: a small allowance, a shopping game, or comparing prices at the grocery store. The best place to start is with something small and repeatable. If your household already has some routines in place, your child will learn without feeling like they’re being “taught” all the time—and that’s what makes the learning stick.
Frequently Asked Questions About Financial Education for Children Ages 5 to 7
At What Age Should You Start Teaching Children About Money?
You can start before age 5, but between ages 5 and 7, children can take part in simple choices with greater understanding. At this stage, use concrete examples, such as buying, saving, and waiting. The goal isn’t to teach banking math; it’s to build an understanding of exchange, limits, and priorities. The sooner money becomes part of the routine, the less unfamiliar the subject will feel later.
Do Children Ages 5 to 7 Understand What Money Is?
Yes, as long as the idea is concrete. Children understand that money is used to trade for things, that they can’t get everything, and that sometimes they need to wait. They’re not yet ready to understand abstract concepts like formal budgeting, interest, or investing. That’s why short phrases and everyday situations work better than long explanations. They learn through experience, not theory.
Is It Worth Giving an Allowance at This Age?
It can be, if the family wants to use an allowance to practice making choices and sticking to a routine. The amount should be small and predictable, with simple rules and no bargaining or punishment. If the child still struggles with basic frustration, it may be better to start with a piggy bank and small choices at the grocery store. An allowance helps when it becomes part of the routine; it loses its value when it depends on the adult’s mood.
Which Games Help Teach Children About Money?
The best activities involve making choices: a pretend store, a piggy bank, a play grocery store, an “now or later” box, and comparing prices with play money. They work because they introduce real limits in a safe environment. At this age, learning through play is much more effective than hearing abstract explanations. The game teaches without feeling like a lecture.
How Can You Talk About Money Without Creating Anxiety or Encouraging Excessive Spending?
Talk about money as part of everyday life, not as a constant problem or a promise of something to buy. Avoid language that creates fear, guilt, or a sense of total scarcity. Show that there are limits, but also that planning is possible: saving, choosing, and waiting are normal parts of life. When adults set this example calmly, children learn to handle money without thinking everything depends on impulse or instant rewards.
Artigos Relacionados
 Passive Income: A Complete Beginner’s Guide to Building Financial Freedom
 Does Creative Education Develop Critical Thinking? An Analysis
 How to Encourage Creativity in Children: 7 Practical Strategies
 Financial Education in Schools: Real-World Results
 5 Teaching Methods That Work for Financial Education
 Why Teens Need Financial Education
