
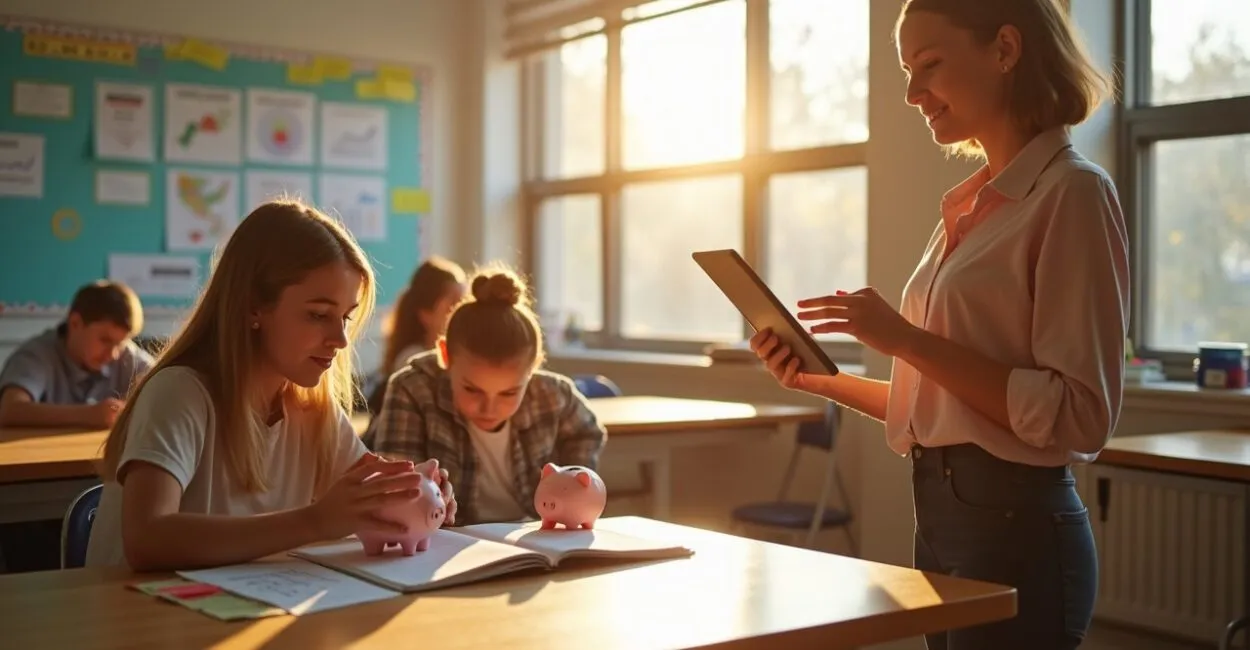
A class learning percentages can calculate the discount on a purchase; a class that also discusses budgeting can compare the discount with the total cost and decide whether the purchase is worth it. That difference helps explain what’s at stake when comparing financial education in schools with traditional teaching: knowledge tied to everyday decisions, alongside academic content. Possible outcomes include a better understanding of financial concepts and more practice planning expenses. This doesn’t guarantee that students will save more or avoid debt in the future: those behaviors also depend on family income, available opportunities, and each person’s experiences. To compare the approaches, it’s important to look at what students learn and how they apply that learning.

At a glance
- Search intent: informational, with a comparison of approaches.
- Definition: financial education is the process of developing the knowledge and skills needed to make decisions about money.
- Grade level: it can be taught from the early grades, using age-appropriate activities.
- Curriculum integration: math, social studies, and school projects can address different aspects of the topic.
- Assessment criteria: knowledge, planning, decision-making, and reflection on consequences.
Financial education in schools versus traditional teaching: what results to compare
Financial education in schools adds situations to the curriculum in which students use financial concepts to analyze choices, while traditional teaching tends to prioritize subject-specific content and exercises with set answers. The difference may show up in applied knowledge and the quality of students’ reasoning; lasting changes in habits, debt, or well-being aren’t automatic and require follow-up. Technically, financial education is the development of knowledge, skills, and attitudes that help people identify options, weigh consequences, and make informed decisions about financial resources. In everyday terms, it means learning to plan how to use money, compare alternatives, and understand commitments such as interest and installment payments.
The two approaches can coexist. A math class can teach percentages; a financial education activity can use that content to calculate the cost of a purchase paid for in installments. The educational benefit comes from connecting the calculation to the decision without sacrificing mathematical rigor.
What changes in teaching goals and methods
Traditional teaching organizes learning by subject and content, such as operations, fractions, or reading comprehension. Financial education in schools builds on that knowledge and introduces real-world problems: creating a mock budget, comparing prices, or discussing the difference between needs and wants.
Brazil’s Base Nacional Comum Curricular (BNCC), the national curriculum framework, calls for contemporary topics to be taught across subject areas. The Base Nacional Comum Curricular provides a framework for integrating relevant topics into different fields of study, although implementation varies by school system and curriculum plan.
One detail that often makes a difference in an activity is distinguishing the cash price, the amount of each installment, and the total cost. If students look only at the size of the monthly payment, they may conclude that the most affordable option this month is also the cheapest. Asking students to explain their decision-making criteria reveals more about their learning than checking only the final answer.
Which results can be measured, and what are the limits

The most direct result of a school-based program is students’ understanding of concepts and their ability to apply them to tasks related to what they’ve been taught. Process indicators can also be observed, such as creating a spending plan, recognizing interest, or explaining a choice. Savings, debt, and financial well-being, however, depend on factors the school can’t control.
Read also: Understanding Personal Financial Education
| Area | What schools can assess | Limits of interpretation |
|---|---|---|
| Knowledge | Understanding of budgeting, interest, prices, and planning. | Answering a question correctly doesn’t prove that students will apply the concept outside the classroom. |
| Decision-making | Comparing options and explaining choices based on costs and goals. | A simulation doesn’t reproduce all the pressures involved in a real decision. |
| Financial habits | Planning expenses in activities or voluntary record-keeping. | Income, family responsibilities, and access to services influence these habits. |
| Well-being and debt | Thinking critically about risks and credit, and finding reliable information. | These are long-term outcomes influenced by broad economic and social factors. |
The OECD treats financial literacy as one of the competencies needed to make informed decisions. Its materials and assessments help organize concepts and compare knowledge, but they don’t justify attributing every change in behavior to a school subject. To evaluate a program, schools can combine assessments before and after instruction with follow-up on the skills taught, without promising effects they haven’t measured.
Read also: Industry-School Partnerships: Benefits for Students and Businesses
How to teach using situations students can relate to
Effective activities start with a problem students can understand at their age and leave room for them to explain their choices. For younger children, this might be a game about allocating limited resources; for teenagers, it could involve budgeting, credit, digital spending, and setting goals.
- Mock budget: Allocate a fictional amount among expenses and explain priorities.
- Shopping comparison: Compare unit prices, discounts, and the cost of paying in installments.
- Class project: Plan the resources for a school activity, document decisions, and revise the plan.
Families can take part without disclosing their household income or debt. A conversation about comparing two offers or planning a goal is enough; asking students to share their family’s financial circumstances can cause embarrassment and create inequality within the classroom.
Why implementation depends on the school and teacher training
A program can fall short when it becomes a one-off lecture, disconnected from the curriculum and without an opportunity to practice. Teachers also need reliable materials and training to cover interest, credit, and spending without turning class into a sales pitch for financial products.
Resources and conditions vary between public and private schools, but that distinction doesn’t support the conclusion that one group always provides better instruction. Quality depends on specific factors, such as continuity, teacher preparation, administrative support, and activities suited to the local context. The Central Bank of Brazil offers financial citizenship resources that can inform lesson planning, alongside teaching materials aligned with students’ grade levels.
There’s also an equity limitation: teaching students to plan can broaden their knowledge, but it can’t replace adequate income, social protections, or fair access to services. If lessons treat financial hardship as an individual failing, they may reinforce stigma rather than build analytical skills.
How to evaluate a program or reinforce learning at home
When evaluating a program, look for clear learning objectives, a sequence of lessons throughout the year, and assessments that match what’s being taught. Also ask how the topic connects to math and other subjects, what materials are used, and how student privacy is protected.
If the school doesn’t offer this content yet, families can use everyday decisions as teaching moments without placing adult responsibilities on children. Planning a small goal, comparing prices, or talking about the difference between a want and a need can teach vocabulary and reasoning; there’s no need to share details about household debt or budgets.
A practical first step for a school is to choose a topic already in the curriculum, such as percentages or reading tables, and create an activity in which students compare alternatives. Then record what they were able to explain and where they struggled. This assessment will guide the next lesson better than a vague promise to create responsible consumers.
Frequently asked questions about financial education in schools
What’s the ideal age to start learning about financial education?
There’s no single ideal age: the content should match a child’s development. In the early grades, simple choices and goal planning are appropriate; credit, interest, and more detailed budgeting make sense when students can work with those concepts.
Does financial education replace math classes?
No. It can apply math concepts, such as percentages, operations, and reading tables, to financial decisions. Math instruction is still necessary for understanding these concepts in depth.
Do private schools provide better financial education than public schools?
There’s no basis for making that claim across the board. The availability and quality of instruction depend on each school’s curriculum plan, teacher training, resources, and continuity.
How can families reinforce the topic at home if the school doesn’t teach it?
Use simple situations, such as comparing prices, planning a pretend purchase, or talking about a savings goal. Avoid exposing children to financial worries that adults should handle or asking them to reveal family information.
Can financial education reduce social inequality, or might it increase it?
Instruction can expand useful knowledge, but it can’t eliminate inequalities in income and access on its own. If lessons blame people facing economic hardship or assume all families have the same opportunities, they can reinforce stigma; a context-aware approach reduces this risk.
When comparing programs, prioritize evidence of learning that the school can observe and avoid promises of guaranteed financial change. The next step is to choose an activity connected to the curriculum, see what students can explain, and adjust instruction based on their responses.
%%AGPTRH3%%
Artigos Relacionados
 5 Teaching Methods That Work for Financial Education
 Why Teens Need Financial Education
 Women’s Leadership in Education: Strategies and Challenges for Inspiring Women Transforming Schools and Communities Around the World
 Traditional vs. Progressive Education: Which Should You Choose?
 What Age Should Kids Start School in Europe? A Guide
 Indigenous Education: Traditional Knowledge in Childhood
