
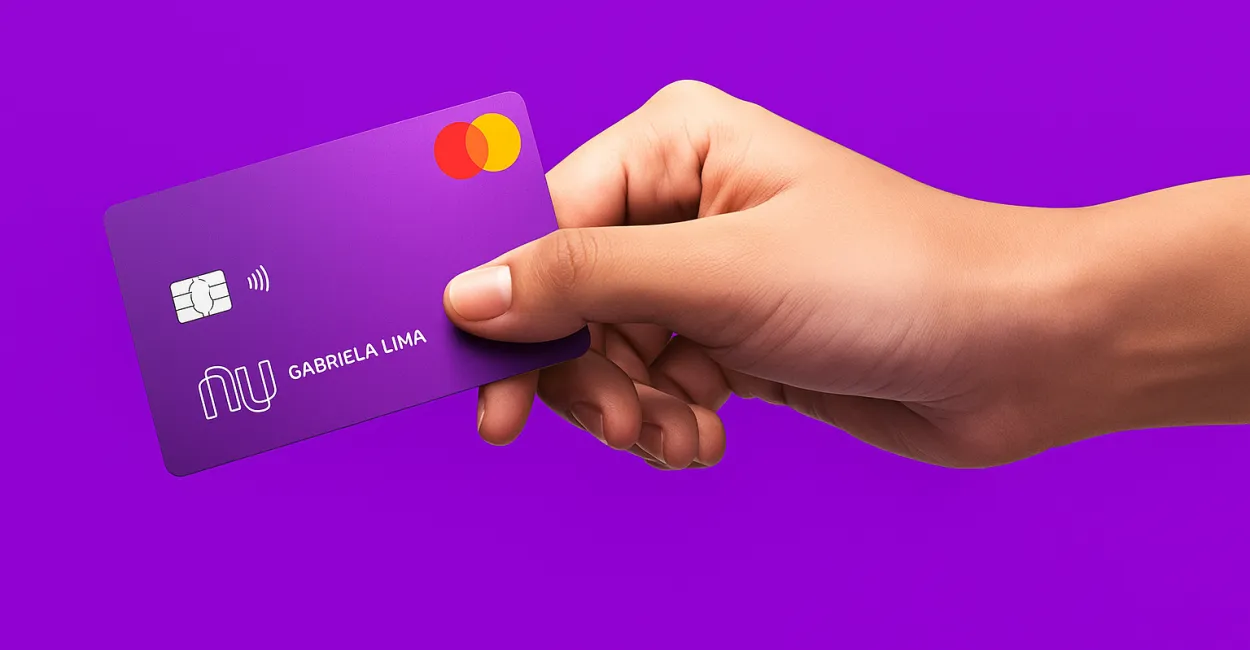
A credit card can be a high-risk product for anyone who loses control of their spending—and one of the most useful tools for those who know how to make their credit limit, statement, and due date work in their favor. With the Nubank credit card, the key difference isn’t just the lack of an annual fee. It’s how the app transforms a line of credit into something visible, trackable, and easy to manage.
That matters because few people go into debt for “lack of a credit card.” The problem is almost always managing the bill, using revolving credit, or getting a false sense of financial breathing room from an available credit limit. This article explains how the purple card works, what it does well, where you need to be careful, and how to avoid interest charges and end-of-month surprises.

What You Need to Know
- Nubank’s card is an internationally accepted credit card managed through an app, with a focus on transparency around your bill, credit limit, and card lock.
- No annual fee doesn’t mean no costs: interest on revolving balances, installment plans for your bill, and late payments still apply.
- The product’s biggest advantage is operational: you can track spending in real time and make everyday spending easier to manage.
- The downside emerges when you treat your credit limit as extra income. That’s when the card stops being a tool and becomes debt.
- To get the most out of the purple card, you need to understand your statement closing date, due date, and bill details.
Nubank Credit Card: How It Works and What Changes Day to Day
Technically, the Nubank credit card is a payment method that lets you pay later, with a preapproved credit limit, a future payment date through your bill, and digital account management handled in the app. Put simply: you buy now, your charges are consolidated later, and you can adjust almost everything without calling customer service or waiting in line.
The Basics: Credit Limit, Statement, and Due Date
Your credit limit is the maximum amount you can spend during a billing cycle. Your statement brings those purchases together in a single document with a monthly due date. Paying the full balance avoids interest.
If you pay late, you may be charged a late fee and interest, and in some cases, IOF—a Brazilian tax on credit and financial transactions.
The system sounds simple, but it can significantly affect how you use the card. By checking your statement in the app, you can decide in advance whether to pay in installments, make purchases early, or wait until the next billing cycle.
People who ignore their statement often find out too late that a credit card doesn’t “increase your income”—it just lets you spend sooner.
Features That Make the App the Center of the Experience
The app lets you lock and unlock your card, create a virtual card, adjust your credit limit, track purchases in real time, and view past statements. It also commonly offers features like contactless payments and instant notifications, which can help you spot unauthorized activity sooner.
In practice, greater visibility leaves less room for error. I’ve seen cases where a user had forgotten about a small purchase, but an app alert helped them check the transaction before the statement closed.
Those details matter when money is tight.
A credit card becomes less risky when you treat your credit limit as a way to manage cash flow, not as money you have available to spend.
How NuConta, Virtual Cards, and Installment Payments Fit In
Nubank’s ecosystem often connects its digital account, virtual card, and installment options offered by merchants. A virtual card is useful for online purchases because it limits how often you share your physical card details with websites and recurring subscription services. Installment options depend on the merchant’s policy and the terms shown in the app at the time of purchase.
This integration makes the experience smoother, but you still need to read the terms carefully. An interest-free installment plan can be a good deal, but not in every situation: if your budget is already stretched, splitting a purchase into multiple payments only prolongs the strain. The benefit is real, but it can backfire when consumers mistake convenience for affordability.
Costs, Interest, and the Rules That Really Affect Your Wallet
The product’s biggest selling point is that Nubank’s standard credit card has no annual fee, but that doesn’t make it free to use. Late payments, minimum payments, revolving balances, and installment plans for your bill are the costs that can really add up. From a risk perspective, these matter more than the annual fee itself.
Key Costs to Watch For
- Annual fee: Nubank’s standard card is known for having no annual fee.
- Revolving credit: Applies when you pay less than your full statement balance.
- Installment plan for your bill: An alternative to paying in full, but it comes with charges.
- Late payment: Usually adds a late fee as well as interest, and makes it harder to stay on top of your finances.
For information about credit rules in Brazil, visit the Central Bank of Brazil at bcb.gov.br. Its regulatory guidance can help you understand what you’re being charged, why interest rates vary, and how financial institutions are required to present information to customers.
Revolving Credit Isn’t a Solution—it’s a Warning Sign
Revolving credit applies when a cardholder pays only part of the statement balance and carries the rest into the following month. It’s one of the most expensive forms of consumer financing, so treat it as an exception, not a strategy.
Here’s an important distinction: paying the minimum may feel like immediate relief, but it tends to push the problem into the future at a higher cost. Anyone who manages a household budget knows that the snowball effect often starts with small unpaid statement balances piling up over two or three months.
Credit card interest doesn’t just penalize late payments; it penalizes repeated disorganization.
Consumers can also consult financial education resources from Procon-SP, a consumer protection agency in the state of São Paulo, at Procon-SP. It explains basic rights related to billing, contracts, and debt negotiation. These resources can be useful because people often skim digital contracts—and that’s when they accept terms without realizing their true impact.
Benefits That Set the Purple Card Apart

The card gained popularity in Brazil by addressing three common frustrations at once: bureaucracy, lack of transparency, and hassle. Instead of relying on in-person service or hard-to-understand statements, customers can check everything on their phone in just a few taps.
Read also: Credit Scores: What They Are and How to Improve Yours
Transparency and Real-Time Control
One of the biggest advantages is seeing purchases appear right away, along with the amount, category, and date. This helps you avoid going over budget and gives you a chance to correct course before your statement closes. With traditional cards, tracking spending can sometimes mean using less intuitive online banking tools or deciphering unclear statements.
Virtual Cards for Online Shopping
A virtual card reduces risk when shopping online or paying for subscription services. If your information is exposed or you spot an unauthorized charge, replacing the virtual card number is usually easier than replacing your entire physical card.
Read also: Santander Credit Card: Complete Guide to Benefits and How to Apply
Card Locks, Unlocks, and Credit Limits at Your Fingertips
Temporarily locking your card, lowering your credit limit, and tracking spending by category give you more control. If you’ve dealt with card fraud, a lost card, or impulse spending, these features can be especially valuable.
Not every benefit works for everyone. People who make a lot of in-person purchases and need high credit limits, or who want robust rewards programs, may prefer other products. A card’s real value depends on how you use it, not on the marketing around it.
Limitations and When This Card May Not Be the Best Choice
The card is great for simplicity, but that doesn’t mean it’s right for everyone. If you’re looking for premium perks, airport lounge access, frequent points transfers, or extensive airline rewards, the basic package may feel too limited.
Who’s Most Likely to Get the Most Out of It
- People who want a no-annual-fee card with digital account management.
- People who shop online frequently.
- People who prefer a clean app, instant notifications, and control over their account.
- People who are building better financial habits.
Who Should Think Twice
If you tend to pay only the minimum amount due, this card can become a problem faster than it becomes a solution. If your monthly budget is already unstable, a preapproved credit limit may give you a false sense of having cash on hand. And if you’re looking to earn rewards aggressively, compare other options on the market before deciding.
The key point is this: a simple card is most helpful to people who already have a basic level of discipline. It doesn’t replace financial education; it just makes it easier to put what you’ve learned into practice.
How to Use Your Card Safely and Avoid Unnecessary Interest
The smartest way to use credit is to separate convenience from borrowing. Using a card to consolidate your spending makes sense; carrying debt from one month to the next almost never does. The difference comes down to how closely you track your statement.
Everyday Habits That Work
- Turn on app notifications for every purchase.
- Check your statement at least once a week.
- Use a virtual card for online stores and subscriptions.
- Avoid committing more than a predictable portion of your income.
- For a large purchase, check whether it fits your budget without relying on your next paycheck.
A Real-World Example
A self-employed professional started putting only recurring expenses on her card: streaming services, transportation, and groceries. At first, the available credit felt like a generous cushion. After three months, she realized that unplanned purchases were taking up room on her statement and squeezing her cash flow before the due date.
She got things back on track by setting a personal spending limit well below her card’s credit limit. From then on, the card stopped acting like extra income and became a tool for staying organized. It’s a simple example, but a very common one in real life.
Where Discipline Matters Most
You get the most out of a card when it fits into a budget you’ve already set. People who use their credit limit to spend ahead without reviewing their income and expenses tend to pay a high price for the convenience. With clear rules, you can reduce risk and keep your statement under control.
Comparing Cards and Choosing the Right One
Comparing credit cards isn’t just about looking for a zero fee. You need to weigh costs, customer service, digital experience, benefits, and your spending habits. In some cases, a card with an annual fee may be worth more than a no-annual-fee card if it offers rewards that match how you spend.
Criteria
Nubank card
What to look for in other cards
Annual fee
No fee for the standard card
Check whether the benefits offset the cost
App management
Powerful and intuitive
Check clarity, reliability, and features
Benefits
More focused on simplicity
Compare points, miles, and insurance
Spending controls
Good for daily tracking
Look for reports, categories, and alerts
If convenience is your priority, the purple card usually delivers. If you want to maximize value on travel or large purchases, consider other card networks, rewards programs, and more premium cards. The right choice is the one that fits your routine, not the card everyone’s talking about.
For guidance on consumer rights and billing, you can also visit Consumidor.gov.br, a Brazilian government platform that provides official channels for complaints and mediation. This support can be useful if you have a billing dispute, need to challenge a charge, or are having trouble resolving an issue with your financial institution.
How to Apply, Get Approved, and Improve Your Chances of a Higher Credit Limit
Approval depends on a credit review, your financial history, and the institution’s internal criteria. There’s no single formula because the algorithm assesses risk, estimated income, and payment behavior. In other words, a strong profile helps, but it doesn’t guarantee immediate approval.
What Often Affects the Decision
- Payment history.
- How your income compares with your credit use.
- Your credit score and financial behavior.
- Account activity and consistent personal information.
Getting Approved Isn’t the End of the Process
Getting the card doesn’t mean the process is over. Your credit limit may increase or stay the same, depending on how you use the account and card over time. Paying on time and using credit in a way that matches your income can help build a stronger relationship with the institution.
Everyone’s situation is different. Some people start with a low credit limit and see gradual increases as they use the card responsibly; others choose not to request an increase to avoid the temptation to spend. The best approach is to make the product fit your lifestyle, not the other way around.
Next Steps
The best way to evaluate this card isn’t emotional—it’s practical. Compare your monthly spending, see whether managing your account through the app helps you stay in control, and check whether you can pay your full statement balance without relying on your next paycheck. If you can, the card is likely to be a helpful tool; if not, the credit limit could become a trap.
Before applying or continuing to use the card, consider three things: total cost, your ability to pay on time, and how useful it is in your daily life. This simple check can help you avoid impulse decisions and distinguish convenience from debt. To make a more informed decision, review the credit terms and your budget before putting new purchases on the card.
Frequently Asked Questions
Does the Nubank Credit Card Have an Annual Fee?
Nubank’s standard card is known for having no annual fee. Still, other costs may apply if you pay late, make a partial payment, or use revolving credit. So “no annual fee” does not mean “no cost.”
Does the Card’s Credit Limit Increase Automatically?
There’s no guarantee that everyone will get an automatic increase. The institution reviews your payment history, card usage, and other risk indicators before granting more credit. Paying on time and using credit consistently helps more than repeatedly asking for an increase.
Is It Worth Paying for Purchases in Installments?
It depends on your income and how predictable your budget is. Interest-free installments can make sense for planned purchases, but only if you can comfortably afford each payment the following month. If your budget is already tight, installment payments just put off the problem.
What Happens If I Pay Only the Minimum Amount Due?
The remaining balance moves to revolving credit or another type of financing, both of which can be expensive. This increases your total debt and makes it harder to escape the cycle of interest charges. Whenever possible, pay your statement balance in full.
Is a Virtual Card Safer Than a Physical Card?
For online purchases, yes. A virtual card is generally safer because it limits exposure of your primary card details. Still, security also depends on the website, your phone, and your own habits. Weak passwords and phishing scams remain risks.
Is This Card a Good Fit for Someone New to Credit?
It can be, as long as you’re disciplined about tracking your statement and avoiding spending beyond your means. The app’s interface can make it easier to learn the ropes, which is helpful for beginners. But if you don’t have your finances under control yet, you’ll need to use the card more carefully than someone with more experience.
Artigos Relacionados
 Pharmacist: A Complete Guide to the Profession and Career Opportunities
 Writer: A Complete Career Guide and Essential Writing Tips
 Insurance Broker: A Complete Guide to the Profession
 Study Time for Civil Service Exams: A Complete Guide to Managing and Improving Your Preparation
 Federal Council of Medicine: A Complete, Updated Guide
 Photographer: The Complete Guide to Mastering the Profession
