
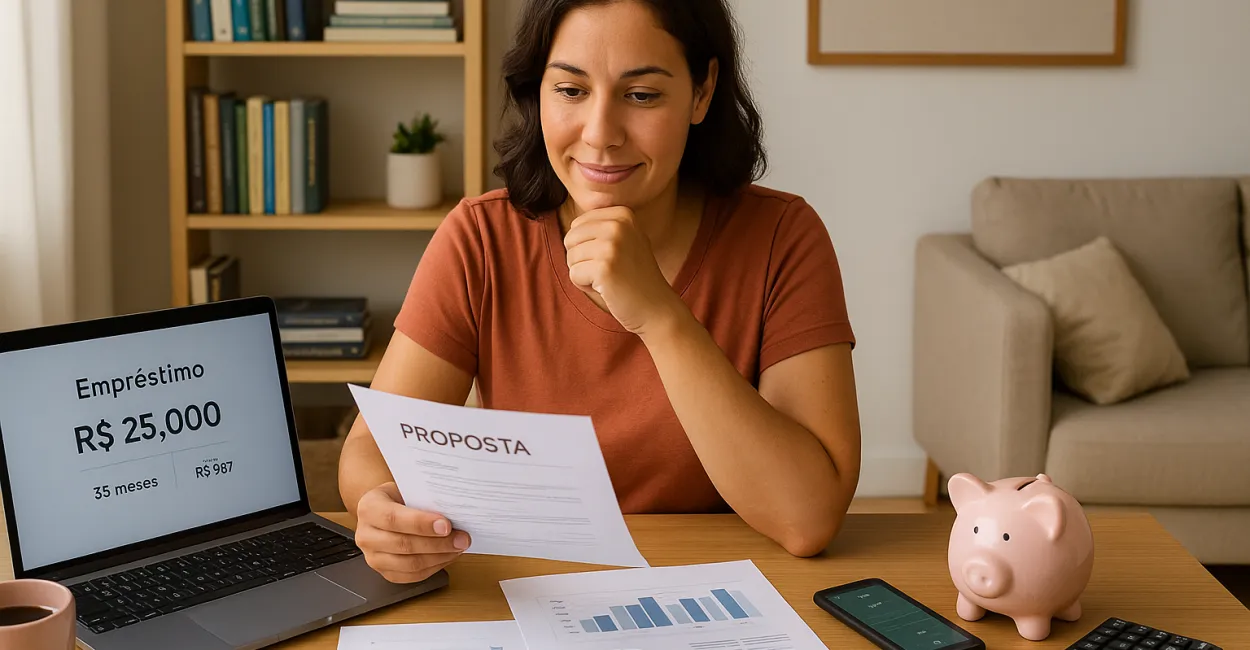
When money is tight, the costliest decision isn’t always borrowing—it’s borrowing without comparing your options. That’s where personal loans come in: a fast financing option, usually unsecured, that can cover expenses, consolidate debt, or fund a project that can’t wait.

In practice, a personal loan can solve an urgent problem in a matter of hours, but it can also turn into a long, expensive debt if you focus only on the monthly payment. This article explains how personal loans work, their real advantages, where the risks lie, and when they actually make sense.
What You Need to Know
- A personal loan is a loan you can use for any purpose, usually with a quick application process and an approval decision based on the borrower’s risk profile.
- The real cost goes beyond interest: the total effective cost, taxes, loan term, and bundled insurance can all change the amount you ultimately pay.
- Personal loans can be useful for emergencies, consolidating expensive debt, and expenses with a planned return.
- They’re less useful for covering recurring expenses, because the loan solves this month’s problem but creates a squeeze next month.
- Comparing monthly payments without looking at the total cost is the most common—and most expensive—mistake.
Personal Loans And The Impact On Your Monthly Budget
Technically, a personal loan is a loan that isn’t tied to a specific purpose. It’s offered by a bank, finance company, fintech company, or credit union, and repaid in installments with interest. Put simply, the money goes into your account and you decide how to use it, but the repayment amount and schedule come with a price and a deadline.
That flexibility is what makes personal loans so popular. At the same time, it calls for more discipline.
Because the loan isn’t backed by collateral, as an auto or mortgage loan is, the lender prices the risk based on income, payment history, credit score, and debt capacity.
How The Application Is Reviewed
Lenders look closely at four areas: verified income, monthly debt obligations, payment behavior, and your relationship with the institution. In many cases, you may be approved but offered a higher rate because your profile is considered risky.
In practice, two people who apply for the same amount can receive very different offers. That’s not simply arbitrary; it’s risk-based pricing.
A borrower with steady income and a clean payment history will usually qualify for better terms than someone with a recent late payment or high credit card balances.
A personal loan may seem like one standard product, but the final cost depends far more on the borrower’s profile and chosen loan term than on the type of loan itself.
The Real Benefits That Make Personal Loans Popular
Fast Funding And Flexible Use
This is the best-known benefit, and for good reason. With online offers, you may get a decision the same day, and the money often arrives quickly when the application review is automated.
When you need to pay for a repair, cover a medical bill, or avoid falling behind on another obligation, speed matters.
Replacing More Expensive Debt
One of the best uses for a personal loan is replacing revolving debt with predictable, fixed installments. Credit cards and overdraft lines, for example, often cost much more than a well-negotiated personal loan. If switching reduces the total effective cost, it can provide real relief for your budget.
Managing Short-Term Cash Flow
Sometimes the problem isn’t a long-term lack of money, but a temporary mismatch between income and expenses. A personal loan can help you get through that gap without turning to even worse options. The key is not to turn a short-term bridge into a monthly habit.
Reference data can help put this market in perspective and compare offers. To understand how consumer credit works in Brazil, consult the Banco Central (Brazil’s Central Bank) credit statistics, which track changes in credit portfolios and borrowing costs. The Banco Central’s interest rate comparison tool lets you compare rates across institutions.
The Costs Many Borrowers Notice Only Later

Nominal Interest Rates Don’t Tell The Whole Story
Looking only at the monthly interest rate isn’t enough. What really matters is the CET, or Custo Efetivo Total (total effective cost), which includes interest, IOF (Brazil’s tax on financial transactions), fees, and, in some contracts, insurance. Two offers with the same monthly payment can have very different total costs.
A Longer Term Lowers The Payment But Raises The Total Cost
This is one of the most common tricks in the market. The monthly payment looks “affordable,” but the repayment period gets longer and the total amount paid goes up. Lenders know that longer terms sell well because they ease the pressure on your wallet today, even though they make the loan more expensive over time.
Variable Rates And Offers With Hidden Conditions
Some offers look attractive at first but become more expensive because of clauses borrowers may overlook. This can happen with advances, automatic renegotiation, or bundled products. Read the contract carefully, because the advertised payment isn’t always the right figure to use for comparison.
For general consumer protection guidance, the Brazilian government’s official credit and debt platform offers useful advice on responsible borrowing and renegotiation. PROCON-SP, São Paulo’s consumer protection agency, also publishes recurring alerts about abusive contract terms and precautions to take when borrowing.
Read also: Credit Cards: Using Them Wisely to Get Through a Financial Crisis
| Criteria | Personal loan | Credit card balance | Overdraft line |
|---|---|---|---|
| Use | Flexible | Flexible | Flexible |
| Cost | Moderate to high | Very high | Very high |
| Predictability | High | Low | Low |
| Risk of a debt spiral | Moderate | High | High |
When A Personal Loan Makes Sense And When To Avoid One
Situations Where It Can Make Sense
A personal loan tends to work best in four situations: an unavoidable emergency, replacing more expensive debt, buying something with lasting value, and managing a temporary cash flow gap. In these cases, it addresses an existing problem with a clear end date.
Read also: Common Mistakes When Applying for Credit: How to Avoid Them and Succeed in 2025
Signs It’s A Bad Idea
If you’re borrowing to fund recurring expenses, trips without savings set aside, impulse purchases, or to “fill a gap” every month, you’re already using the loan poorly. That’s not financial moralizing; it’s math. Today’s payment becomes tomorrow’s shortfall.
A common example: someone borrows $5,000 to pay off a credit card, lowers their interest costs, but keeps using the full credit limit every month because they haven’t changed their spending habits. Two months later, the card balance is climbing again, and the loan payment is still coming out of their budget. The result is a double burden: the old debt was replaced, but the original problem remains.
A personal loan can help when it fixes a temporary imbalance; it gets in the way when it becomes an extension of income you don’t have.
How To Compare Offers Without Falling For A Low Monthly Payment
Always Compare The Total Effective Cost
This is the figure that should guide your decision. If the lender doesn’t clearly disclose the total effective cost, be cautious. The interest rate may catch your eye, but the total effective cost should determine your choice.
Match The Loan Term To Your Actual Budget
Before signing, plan for your worst likely month, not your best one. If the payment only works when everything goes right, you can’t truly afford it. A good rule of thumb is to leave room in your budget for emergencies, because they don’t give you advance notice.
Read The Loan Terms
Check for payment deferrals, late fees, early repayment terms, and insurance charges. With some contracts, paying off installments early can significantly reduce the cost. With others, the savings are smaller than they seem. The details vary by contract, so don’t assume the same rules apply everywhere.
Signs Of A Safer Loan Contract
Clear Information
A reliable offer clearly shows the amount you’ll receive, interest rate, total effective cost, term, number of payments, and total cost. If the offer uses confusing language, flashy banners, and hidden details, the chance of trouble goes up.
Fits Your Income
The best loan is one you can repay without straining your budget. No financial strategy can make an unaffordable payment fit your circumstances. When the payment takes too much out of your monthly budget, the loan stops being a solution and becomes a source of late payments.
A Regulated Lender And A Way To Check Its Records
Choose institutions authorized to operate in Brazil and check their reputation through consumer protection channels. The Banco Central’s Registrato service can also help you check your financial relationships and track your debt, giving you a more accurate picture of your situation.
The Most Common Mistakes People Make When Borrowing Without A Plan
Borrowing More “Just In Case”
Extra cash may seem like a smart cushion, but it usually becomes an unnecessary expense. If you don’t need the full amount, don’t pay interest on money that will just sit in your account.
Using A Loan To Cover Ongoing Disorganization
When a loan covers a structural shortfall, the cause of the problem is still there. It’s like pouring water into a leaky bucket: things improve for a moment, then the problem comes right back.
Ignoring Your Exit Plan
Before borrowing, the right question isn’t “Can I afford the payment?” It’s “What habit, expense, or debt will I address so I don’t have to do this again?” Without a clear answer, taking out a loan becomes an expensive quick fix.
Next Steps For Making A Better Decision
If you want to borrow responsibly, treat an offer as a financial comparison, not an emotional solution. Do the math based on the total amount, check the total effective cost, plan for a late payment, and make sure the monthly payment will still be manageable in a tough month. This filter can prevent many bad decisions before they happen.
To move forward safely, compare at least three offers, check the early repayment policy, and proceed only if the loan addresses a specific problem. Instead of looking for “the lowest payment,” look for the loan with the lowest total cost that comfortably fits your budget. The best loan is one that improves your life without creating a second, hidden debt.
Frequently Asked Questions
Do personal loans have lower interest rates than credit cards?
In most cases, yes. Personal loans usually cost less than carrying a credit card balance or using an overdraft line, although that depends on the borrower’s profile and the lender. That’s why comparing the total effective cost is more useful than comparing only the advertised rate.
Is it worth using a personal loan to pay off debt?
It can be if the original debt is more expensive and the new payment fits comfortably in your budget. The switch only makes sense if you stop adding to the old debt; otherwise, the problem will return. When renegotiating debt, discipline matters as much as the interest rate.
Can I pay off installments early and pay less interest?
Yes, and with many contracts that reduces the total cost. The effect depends, however, on how the lender calculates the principal reduction and which charges have already been included. Always check the rules before taking out the loan.
What’s the difference between a personal loan and a payroll-deducted loan?
With a payroll-deducted loan, the payment comes straight out of your paycheck or benefits, which lowers the lender’s risk and usually means a lower rate. With a standard personal loan, you’re responsible for making the payments each month, so the risk and cost tend to be higher. The right choice depends on your income and available borrowing capacity.
How can I tell if the payment fits my budget?
Add up all your fixed expenses, set aside money for emergencies, and see what’s left without counting on uncertain income. If the payment requires drastic cuts or depends on “everything going right” that month, it’s too high. The right test is your actual budget, not an optimistic one.
%%AGPTRH4%%
Artigos Relacionados
 Auto Insurance: What to Know Before You Buy
 Credit: The Essential Engine of Sustainable Economic Growth
 Writer: A Complete Career Guide and Essential Writing Tips
 Nursing Assistant: A Complete Guide to This Essential Profession
 Paid Traffic Manager: A Complete Guide to This Essential Digital Marketing Career
 Networking: Essential Strategies for Building Powerful Professional Connections
