
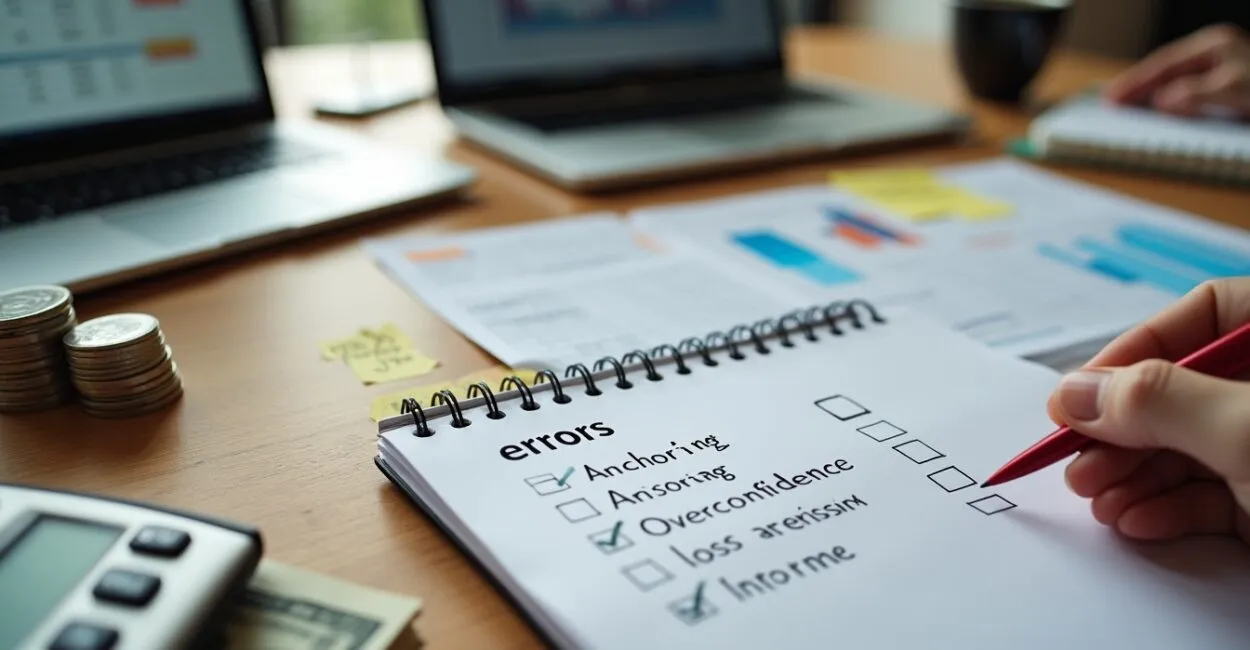
Financial bias is a set of cognitive tendencies that distort decisions about money, investments, and budgets, affecting personal and business outcomes. Understanding financial bias matters because it can help prevent avoidable losses and improve decision-making with practical tools. To get started, identify recurring patterns of mistakes, measure their impact, and apply corrective strategies right away.
In today’s environment, biases such as overconfidence, anchoring, and loss aversion affect professionals, investors, and families. This creates clear opportunities to gain an advantage through structured processes. This article explores common types of financial bias, practical examples, and actionable steps to address them in everyday life, with checklists, comparison tables, and proven practices.

You’ll find definitions, a step-by-step methodology, comparisons of mitigation methods, advantages and limitations, and a set of tips you can apply today to reduce mistakes and improve financial returns.
Basic Definitions and Concepts of Financial Bias
What constitutes financial bias and why it affects decisions
Financial bias refers to mental shortcuts and predispositions that influence judgments about spending, investing, and risk assessment. These biases interfere with the objective perception of probabilities and returns, leading to suboptimal choices that are repeated over time. Understanding these patterns makes it possible to develop interventions that correct deviations and restore financial discipline.
In personal and business settings, financial bias can show up as impulsive decisions, overconfidence, and a tendency to follow the crowd. Identifying the situations in which these biases occur—such as choosing an investment or negotiating a purchase—is the first step toward reducing losses.
Tools such as checklists, automated rules, and peer reviews can turn intuitive decisions into controlled processes, reducing the negative impact of financial bias on assets and results.
Main types of financial bias and their characteristics
Some of the most common biases include overconfidence, anchoring, confirmation bias, loss aversion, herd behavior, and hindsight bias. Each has different triggers: anchoring occurs when initial information skews later evaluations, while loss aversion leads people to avoid selling assets at a loss.
These biases can have measurable effects, such as asset allocation decisions that reduce average annual returns. According to the CFA Institute, behavioral mistakes can reduce individual investors’ returns by as much as 1–2% per year.
Recognizing signs such as emotional justifications, resistance to contradictory data, and repeated mistakes makes it possible to map financial bias in processes and develop effective corrections.
Psychological factors that sustain financial bias
Cognitive factors such as heuristics, emotions, and overconfidence sustain financial bias. Heuristics save mental effort but can distort probabilities; emotions trigger impulsive decisions; and reputation or ego can keep people invested in losing positions.
Social factors, such as peer pressure and cultural norms around consumption, also shape financial choices. This helps explain why groups can amplify collective mistakes and create price bubbles or unsustainable spending spikes.
Behavioral strategies—for example, rule-based decisions, conscious anchoring, and automated contributions—help counterbalance these psychological factors and make financial decisions more rational.
- Heuristics and mental shortcuts
- Loss aversion and regret aversion
- Overconfidence in personal estimates
- Herd behavior and social influence
- Anchoring on inaccurate initial information
A Practical Step-by-Step Guide to Reducing Financial Bias
Preparation: how to map decisions and recurring biases
Start by listing critical financial decisions (investing, saving, using credit) and recording the results from the past 12 months. Map where frequent mistakes occur—for example, selling impulsively after a market downturn or making an impulse purchase during a sale—and identify the emotional triggers associated with each event.
Use simple metrics: how often emotional decisions occur, the resulting losses, and the time spent researching before making a decision. This initial assessment helps you prioritize corrections with a favorable cost-benefit ratio.
Document everything in a spreadsheet and review it monthly; this discipline reduces the influence of automatic biases and creates a history for objective evaluation.
Execution: rules and routines for more rational decisions
Set rules, such as a fixed asset allocation, automatic monthly contributions, and a limit on exposure to any one position. Standardized rules minimize snap judgments and prevent impulsive decisions during emotional highs and lows.
Build in a “cooling-off” period before major decisions (e.g., 48–72 hours) and get a second opinion to check for anchoring and confirmation bias. Digital budgeting tools and investment platforms with automatic orders can help you follow through without bias.
Monitoring key indicators (returns vs. a benchmark, portfolio volatility) helps you assess whether the rules are offsetting financial bias over time.
Ongoing adjustments: measure, review, and improve processes
Set up quarterly review cycles to assess quantitative and qualitative metrics: the percentage of decisions susceptible to bias, losses attributable to bias, and adherence to rules. Adjustments should be based on concrete data and testable hypotheses.
Use controlled experiments (for example, comparing decisions made with and without a checklist) to validate changes. A culture of continuous improvement turns one-off corrections into established practices, reducing repeat mistakes.
According to Behavioral Economics, simple interventions can reduce behavioral mistakes by as much as 30% in controlled settings, demonstrating significant potential gains.
- Map critical decisions and record 12 months of history.
- Implement automatic rules (contributions, allocation, limits).
- Build in a “cooling-off” period before major decisions.
- Review metrics quarterly and adjust processes.
Comparing Methods for Mitigating Financial Bias

Quantitative analysis versus behavioral interventions
Quantitative methods (backtesting, risk models) reduce bias through data; behavioral interventions (checklists, nudges) address behavior. Combining both is the most robust strategy: data informs the rules, while nudges support follow-through.
Quantitative models require historical data and may fail during extreme events; behavioral interventions can work even amid uncertainty, but may be less precise when mathematically optimizing returns.
Combining simulations with behavioral tests in controlled settings provides a practical balance between precision and real-world applicability.
Automation versus human oversight
Automation eliminates emotional decisions and supports discipline (e.g., scheduled contributions), while human oversight identifies exceptions and puts unprecedented events in context. The ideal is a hybrid system: automated rules for routine decisions and human review for exceptions.
Automating processes reduces frequent errors but can reproduce biases built into poorly designed rules. Periodic oversight and rule audits are essential to correct embedded biases.
Companies that combine automation with human governance tend to have more resilient and adaptive financial processes, reducing the impact of organizational financial bias.
Comparing the effectiveness of practical approaches
Some approaches are quick and inexpensive (checklists, waiting periods), while others require investment (optimization software, consulting). Effectiveness depends on the context: individuals benefit more from simple automation, while organizations need structured governance.
Comparative data helps prioritize investments—for example, according to industry studies, setting up automatic contributions can increase savings by 10–20% over 12 months.
Choosing the right combination depends on risk profile, asset size, and the resources available for monitoring and correction.
| Method | Advantage | Limitation |
|---|---|---|
| Automated contributions | Discipline and consistency | Requires periodic adjustments |
| Checklists | Low cost and quick to use | Depends on user adoption |
| Quantitative models | Data-driven optimization | Sensitive to modeling errors |
| Behavioral nudges | Automatically influences choices | Requires design and testing |
The Impact and Benefits of Correcting Financial Bias
Improved performance and fewer losses
Reducing financial bias generally improves net returns and cuts down on decisions that result in realized losses. Investors who follow rules and avoid impulsive decisions tend to outperform the average over 3–5-year periods.
According to the CFA Institute, individual investors can lose between 1% and 2% per year due to behavioral mistakes; correcting these mistakes makes portfolios more efficient.
These compounded gains can have a significant effect: for example, an additional 1.5% per year over 20 years represents a considerable increase in accumulated assets.
Greater predictability and risk management
Standardized processes and regular monitoring make results more predictable and simplify risk management. Allocation models and position limits reduce exposure to sharp downturns and extreme events.
Greater predictability helps decision-makers plan cash flow, obligations, and strategic investments with fewer unexpected contingencies.
Organizations that implement financial governance focused on bias report greater operational stability in volatile conditions.
Better behavioral decisions and financial habits
By reducing bias, people develop positive financial habits—saving consistently, diversifying, and reviewing goals. These habits have a long-term impact on financial security and the ability to achieve personal goals.
Simple interventions, such as automating savings, increase the likelihood of meeting financial goals; repetition turns these actions into routines.
There are psychological benefits, too: less financial stress, greater control, and more clarity about future decisions.
- Potential improvement in annual returns
- Greater discipline and consistency in decision-making
- Reduced exposure to avoidable risks
- More predictable cash flow
- Improved personal financial habits
Advantages and Disadvantages of Financial Bias Interventions
Main benefits of adopting corrective measures
Interventions can reduce impulsive decisions, improve discipline, and potentially increase returns. Implementing rules and automation saves time and reduces the opportunity costs caused by poor investments.
In addition, stronger governance supports audits and compliance in corporate settings, bringing reputational and operational gains over time.
Studies show that small behavioral changes can produce measurable improvements in financial performance, making interventions cost-effective in many cases.
Limitations and risks of these approaches
Some interventions can involve implementation and maintenance costs (software, consulting). Poorly designed rules can lead to excessive rigidity, preventing people from adapting to unexpected events.
Automation without regular review can perpetuate errors embedded in the rules, while poorly designed nudges may be ineffective or ethically questionable if they manipulate choices without transparency.
It’s essential to balance automation with human review and auditing to address limitations and reduce the risk of adverse effects.
How to choose the right intervention for your situation
The choice depends on asset size, level of sophistication, and acceptable costs. For individuals, starting with simple automation and checklists can deliver strong returns at a low cost. Organizations should prioritize governance, reviews, and alert systems.
Test on a small scale before expanding; validate hypotheses with data and adjust rules based on practical needs and stakeholder feedback.
When selecting an approach, estimate its cost-benefit ratio and set clear success metrics to evaluate how effective the interventions are.
- Fewer impulsive decisions
- Greater financial discipline
- Improved risk management
- Upfront investment required
- Possible excessive rigidity if poorly implemented
- Requires ongoing review
- Greater transparency and governance
| Feature | Advantage | Disadvantage |
|---|---|---|
| Automation | Discipline | Less flexible |
| Checklists | Low cost | Depends on the user |
| Modeling | Informed decisions | Requires data and maintenance |
Disadvantages and Limitations of Addressing Financial Bias
Implementation costs and effort
Implementing solutions to address financial bias can take time and require investment in tools, training, and governance. Small changes are inexpensive, but comprehensive systems require resources and organizational discipline.
Companies may need to set aside a budget for consulting, software, and monitoring, while individuals may need to invest time in financial education and setting up automation rules.
Planning costs and implementation phases minimizes financial impact and ensures incremental returns on investment.
Risks of complacency and overconfidence in rules
Rules and automation can create a false sense of security; if they aren’t reviewed, they may fail during unusual events. Overconfidence in models or checklists can reproduce embedded biases and lead to unexpected losses.
Regular reviews and stress tests help identify flaws and adapt rules to new scenarios, reducing the risk of complacency.
Combining human oversight with automation corrects distortions and preserves the ability to respond to market shocks.
Limited effectiveness in extreme situations
Behavioral interventions have limited effectiveness during macroeconomic crises; in highly volatile events, collective emotional reactions can override rational processes. In these situations, diversification and contingency plans are essential safeguards.
Models and rules may also fail to predict crisis scenarios, so a robust response plan and sufficient liquidity complement measures to address financial bias.
Recognizing limitations and maintaining strategic reserves make bias mitigation more resilient in the face of extreme events.
- Upfront investment required
- Possible complacency about rules
- Less effective during severe crises
Tips and Best Practices for Addressing Financial Bias
Practical processes that are easy to implement
Set up automatic contributions, limits for each investment, and waiting periods before significant decisions. These simple practices can be put in place in just a few hours and require little technology, immediately reducing the impact of biases such as impulsiveness and anchoring.
Use standardized spreadsheets to record decisions and outcomes; this creates a history for analysis and prevents repeated decisions based only on intuition.
Set up monthly or quarterly reviews with clear indicators to assess whether the practices you’ve implemented are being followed and working effectively.
Best practices for monitoring and governance
Define KPIs tied to financial behavior—how often emotional decisions are made, losses from impulsive sales, and adherence to target allocation—and review them regularly. Assign people to oversee governance and establish internal audit processes to detect deviations.
Incorporate third-party feedback and independent audits when possible; this reduces internal biases and strengthens decision quality.
BI tools and automated dashboards make real-time monitoring easier and support rapid corrective action.
How to train teams and individuals to reduce bias
Make training practical: decision-making simulations, case studies, and retrospective review exercises help identify biases. Recurring training (every 6–12 months) reinforces rational habits and updates processes.
Promote a culture of discussion and review, encouraging people to cross-check and document important decisions. This reduces confirmation bias and herd behavior.
According to academic studies, well-designed behavioral training can reduce poor decisions by about 20–30% in controlled settings, improving the quality of financial decisions over time.
- Automate contributions and savings
- Build in “cooling-off” periods before major decisions
- Document and review decisions regularly
- Implement financial behavior KPIs
- Conduct practical training and simulations
Conclusion
Correcting financial bias is essential for improving results and reducing avoidable risks. By applying rules, automation, and systematic reviews, you can increase discipline and predictability. Financial bias can be mitigated with simple, scalable measures, from automatic contributions to structured corporate governance.
Start by mapping your decisions and setting up at least one automated rule today. Reevaluate quarterly and make adjustments based on data; this routine produces consistent gains and protects your assets. Put the practices in this article to work and turn habits into a financial advantage.
Frequently Asked Questions About Financial Bias
What is financial bias?
Financial bias refers to cognitive patterns that distort decisions about money, investments, and budgets. It stems from heuristics, emotions, and social pressures, leading to repeatedly suboptimal choices. Identifying financial bias involves mapping critical decisions, recording outcomes, and understanding emotional triggers. This makes it possible to use rules, automation, and reviews to reduce its impact and improve financial performance over time.
How does the process of mitigating financial bias work?
The process works in cycles: diagnosis (mapping decisions and mistakes), intervention (rules, automation, nudges), and monitoring (KPIs and reviews). Start with simple actions such as automatic contributions and checklists, then move on to quantitative models and governance. Periodic reviews and controlled tests validate effectiveness. This process turns impulsive decisions into predictable, measurable procedures.
What’s the difference between financial bias and financial risk?
Financial bias is a cognitive phenomenon that distorts judgments and decisions; financial risk is the objective possibility of loss associated with an asset or situation. Bias increases the likelihood of decisions that raise risk, while risk can be measured and managed using probabilities and scenarios. Controlling bias supports better risk management practices.
When should I use automation to reduce financial bias?
Use automation when routine decisions are made impulsively or when you tend to procrastinate (such as saving less than you planned). Automation is useful for contributions, periodic rebalancing, and exposure limits. It reduces emotional influence and supports discipline, but it should be reviewed regularly to prevent outdated or poorly designed rules from causing problems.
How much does it cost to implement measures to address financial bias?
Costs vary: basic measures (checklists, spreadsheets, bank automation) can be nearly free, while advanced solutions (portfolio software, consulting, training) can cost hundreds to thousands of dollars. Assess the cost-benefit ratio: small improvements can generate an increase in returns equivalent to 1–2% per year, quickly offsetting the initial investment depending on your assets.
Artigos Relacionados
 How to Choose the Best Online Financial Education Course
 Family Financial Planning: Build Your Financial Freedom
 Understanding Personal Financial Literacy
 Financial Literacy Activities for Kids at School
 The Role of a Financial Advisor in Wealth Management
 Financial Analyst: A Complete Guide to a Successful Career
