
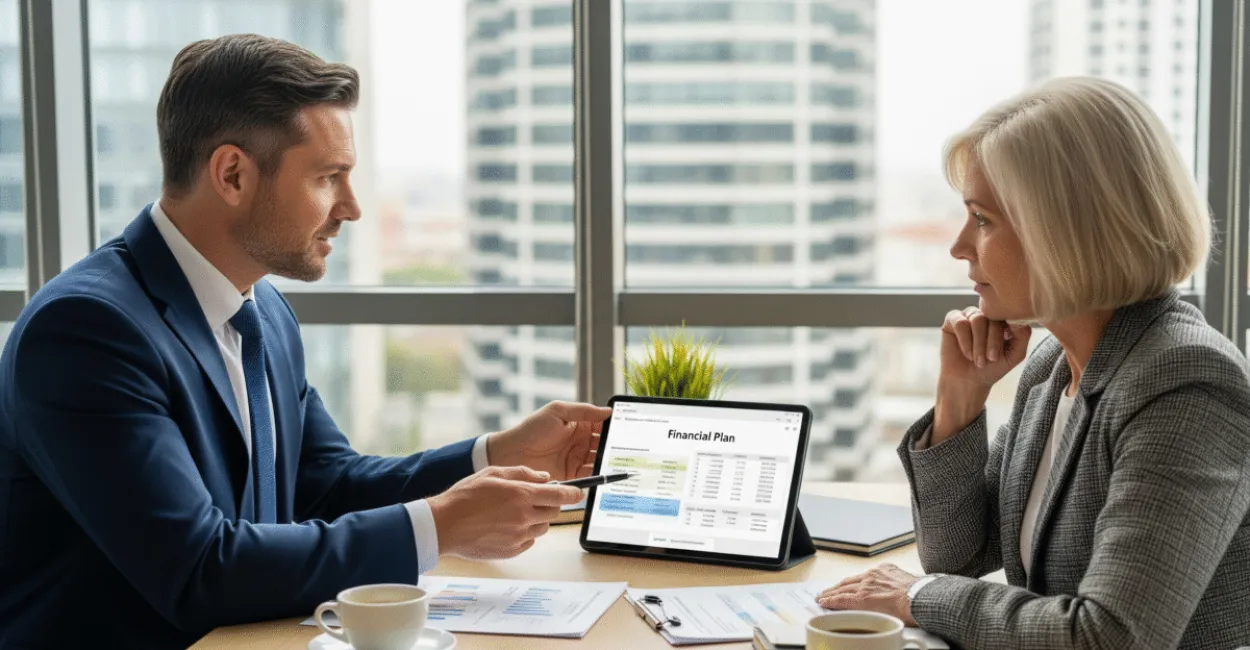
Working with a financial advisor can help you organize your finances, prioritize goals, and make decisions to grow your assets and manage risk. A financial advisor can guide you on investments, retirement, and cash flow management, helping you understand what matters now and how to take action. This practical guidance is essential for anyone looking to preserve and grow their assets amid economic uncertainty.
In today’s environment of inflation, volatile interest rates, and new financial products, professional advice can make a difference in protecting your wealth and making more effective choices. Understanding your options, costs, and risks takes time and expertise—key areas where a financial advisor can help. Below, we explore this professional’s role, methods, benefits, limitations, and recommended practices to help you get the most out of the service.

This article covers definitions, practical steps, strategy comparisons, compensation models, advantages and risks, actionable tips, and answers to common questions about financial advising.
Financial advising: definitions and concepts
The financial advisor’s role in practice
A financial advisor bridges the gap between personal or business goals and solutions in the financial markets. They turn goals into workable strategies by considering risk, time horizon, and liquidity. In practice, that can mean building portfolios, planning for retirement, managing debt, and optimizing cash flow to preserve wealth and pursue returns that fit the client’s risk profile.
The role calls for technical knowledge of markets, products, and taxes, as well as clear communication skills. Advisors may work independently, at banks, or for advisory firms, while complying with applicable regulations. Their work combines assessment, planning, and ongoing support.
In Brazil, advisors are often certified by organizations such as ANCORD, a Brazilian association for capital markets professionals, or hold the CFP designation. These credentials can help demonstrate professional qualifications. Choosing the right advisor can have a direct impact on your financial results over time.
Essential terms to know
Understanding terms such as asset allocation, liquidity, volatility, real return, and correlation is essential when working with a financial advisor. These concepts help explain why a strategy that balances fixed income, equities, and alternative investments can reduce risk and improve the risk-return tradeoff. A good advisor explains these concepts before recommending products.
It’s also important to understand explicit costs (such as management and performance fees) and implicit costs (such as spreads and taxes) when evaluating a recommendation. Transparency about these costs is an important factor when choosing an advisor.
Regulatory and compliance terms also matter. Know your customer (KYC) requirements, suitability standards, and tax rules all affect which products are appropriate for each client’s profile and goals.
Basic concepts
- Asset allocation: Distribution across asset classes (fixed income, equities, and alternatives).
- Risk profile: Conservative, moderate, or aggressive, determining the level of investment exposure.
- Investment horizon: Short-, medium-, or long-term, guiding liquidity needs and investment choices.
- Fees and costs: Directly affect an investor’s net returns.
- Tax planning: Legally optimizing taxes on investments.
Financial advisor processes and methods
How a financial advisor builds a plan
A typical process starts with an assessment of assets, liabilities, income, expenses, and goals. Next, the advisor helps define measurable financial goals, timelines, and risk tolerance. They use this information to develop a personalized strategy, including asset allocation, contribution targets, and rebalancing rules.
Ongoing monitoring and periodic reviews—monthly, quarterly, or annually—help keep the plan aligned with changes in the market and the client’s life. Regular communication is essential for adjusting expectations and taking action.
Financial software and risk analysis models, such as scenario simulations and stress tests, support more robust decisions by helping anticipate how economic shocks could affect a client’s wealth.
Practical steps to get started
- Map out your current financial situation: income, expenses, assets, and debts.
- Set clear goals and timelines (short-, medium-, and long-term).
- Determine your risk profile based on your tolerance and goals.
- Ask for a written plan that includes asset allocation, costs, and performance targets.
- Review the plan quarterly and adjust contributions and allocations as needed.
Tools and technology
Financial advisors use financial planning software, performance dashboards, scenario simulators, and portfolio management tools. These technologies enable real-time analysis, goal tracking, and customized client reports. Integration with investment platforms makes execution and oversight easier.
Robo-advisors and algorithms can complement advisors’ work on passive allocations, while human guidance adds value for complex, tax-related, or estate planning decisions. Combining the two can improve efficiency and reduce operating costs.
Information security and encryption are priorities, helping protect clients’ financial data in line with best compliance practices.
Comparing wealth management strategies

Active vs. passive portfolios
Active portfolios aim to outperform benchmarks through security selection and market timing. They typically have higher costs, such as management and performance fees, and require active oversight from a financial advisor. Passive portfolios track indexes, offering lower costs and greater transparency. The right choice depends on your goals, time horizon, and sensitivity to costs.
Historical data shows that in many markets, fewer than 30% of active managers consistently outperform their index after fees. According to S&P Dow Jones Indices, only about 20%–25% of U.S. managers beat their benchmark over 10-year periods.
An advisor can combine approaches by using index funds for part of a portfolio and active management where there may be an edge, such as in alternative investments or private credit selection.
Comparing investment methods
| Strategy | Typical costs | Best suited for |
|---|---|---|
| Active management | 0.8%–2% per year + performance fees | Investors seeking alpha and willing to accept volatility |
| Passive management | 0.02%–0.5% per year | Long-term investors focused on low costs |
| Tactical allocation | 0.3%–1% per year | Adjustments based on the economic cycle |
| Financial planning | Flat fee or project-based fee | Personal goals, retirement, and estate planning |
Financial planning vs. investment management
Financial planning often involves broad advice and planning, with fees charged by project, hour, or flat rate. Investment management typically includes executing and managing investments on an ongoing basis, with compensation usually tied to assets under management. The right choice depends on how involved the client wants to be and how complex their situation is.
In practical terms, clients who want to stay in control may prefer one-time financial planning, while those looking to delegate routine tasks and decisions may choose investment management. Transparency about conflicts of interest and compensation is essential when assessing an advisor’s independence.
Before hiring an advisor, check their credentials, work history, and references. Clear contracts help avoid surprises about costs and responsibilities.
Compensation models and transparency
Common compensation models
There are three main models: a flat fee for financial planning, a percentage of assets under management (AUM), and commissions on products sold. Flat fees are common for financial planning projects; AUM fees can align interests in an ongoing management relationship; commissions may create conflicts of interest if they are not disclosed. The right model depends on the level of service and the client’s preferences.
According to the Banco Central do Brasil, Brazil’s central bank, fee transparency is critical to investor protection and reducing information gaps. Always look for clear contracts and fee schedules.
Read also: Librarians: Their Essential Role in Modern Society
A committed advisor explains how fees affect net returns and presents options for reducing costs without compromising your goals.
Benefits of the AUM model
The AUM model can align interests: as a client’s wealth grows, the advisor is compensated proportionally. This can encourage a focus on preserving and steadily growing the portfolio. It also makes costs more predictable and combines implementation with ongoing monitoring, reducing the need for approval before every transaction.
However, AUM fees can be costly for investors with smaller portfolios because the fees are proportional to assets. Review fee tiers and minimum account requirements. Compare them with flat-fee alternatives for one-time projects such as estate planning.
Transparency and regular performance and cost reports make this model more reliable when it is implemented well.
Advantages and disadvantages
| Type | Advantages | Disadvantages |
|---|---|---|
| Flat fee | Predictable; ideal for projects | No incentive for ongoing monitoring |
| AUM | Aligned interests; ongoing support | Proportional fees can be high for smaller portfolios |
| Commission | Access to products with no upfront cost | Risk of conflicts; less transparency |
Advantages and benefits of financial advising
Improving returns and reducing risk
A qualified financial advisor can increase the likelihood of reaching your goals by optimizing asset allocation and costs. Rebalancing and diversification can help reduce volatility and prevent emotional decisions that hurt results. Tax planning and choosing appropriate products can also directly affect net returns.
Studies show that strategic asset allocation and disciplined contributions can improve results consistently over time. According to the International Monetary Fund (IMF), diversification reduces concentration risk in specific assets.
Professional guidance can also identify opportunities to improve a portfolio, such as reallocating to assets with a better risk-return profile as economic conditions change.
Tax, estate, and financial planning benefits
Financial advisors can offer guidance on tax-efficient vehicles (such as private pension plans and tax-efficient funds) and estate planning strategies (such as wills and family holding companies). These approaches can reduce costs and help preserve wealth for future generations. Estate planning can prevent disputes and facilitate the transfer of assets with legal protections.
An advisor can also help build an emergency fund and balance liquidity with returns, protecting clients from unexpected events without compromising long-term investments.
These services add value beyond investment management, covering legal and operational issues that matter to families and businesses.
Benefits at a glance
- Decisions based on technical analysis and data.
- Reduced risk through diversification and rebalancing.
- Lower costs and taxes, improving net returns.
- Retirement and estate planning.
- Ongoing monitoring and adjustments to macroeconomic changes.
Limitations, risks, and points to consider
Key limitations of financial advising
Financial advice cannot eliminate market risk or guarantee returns. Recommendations depend on assumptions and scenarios that may change. Conflicts of interest can also arise if compensation and relationships with financial institutions are not disclosed. Clients should check a financial advisor’s credentials and track record before hiring them.
Another limitation is the time it takes to put a plan into action. Wealth restructuring strategies can take months to implement and require discipline and patience. The upfront cost of a customized plan may also be significant for people with smaller portfolios.
Finally, decisions depend on the quality and accuracy of the information the client provides. Incomplete data can make a financial plan less effective.
Operational and compliance risks
Operational risks include order execution errors, platform integration failures, and information security issues. Compliance risks involve violations of regulations, money laundering, and failure to meet regulatory requirements. A responsible financial advisor uses controls, KYC policies, and contract reviews to help mitigate these risks.
Check whether the advisor follows rules set by the CVM, Brazil’s securities regulator, the Banco Central do Brasil, and relevant professional associations. Make sure they use clear contracts that outline responsibilities and service levels. Independent audits and regular reports can build trust.
Clients are responsible for keeping their documents up to date and reporting significant changes in their financial situation or goals.
Disadvantages and limitations
- Returns are not guaranteed; market risk remains.
- Commissions or incentives may create conflicts of interest.
- Advisory fees can be high for smaller portfolios.
Practical tips and best practices for working with an advisor
How to choose the right financial advisor
Look for references, credentials (such as CFP or ANCORD certifications, or registration with the CVM), and clear contract terms. Ask for examples of work with similar clients and sample reports. Initial interviews can help you assess whether your values and communication styles are a good fit. Choose an advisor who provides a written plan with measurable goals and a review schedule. Also check their compliance history and any disciplinary actions.
One good practice is to test the relationship with a pilot project or an initial consultation to see whether you’re a good fit. Before signing a contract, make sure the advisor clearly explains costs, conflicts of interest, and compensation models.
Consider the advisor’s service capacity as well: independent advisors may provide more personalized attention, while larger teams may offer more technology and specialists in different areas.
Putting plans into action and monitoring them
Set clear KPIs (such as expected return, maximum volatility, and withdrawal timeline) and a review schedule. Establish rebalancing rules and limits for tactical changes. Make regular contributions and document significant decisions to make future reviews easier. Your financial advisor should provide quarterly reports showing changes in your assets, returns, and comparisons with benchmarks.
Use online dashboards to track performance and improve transparency. Ask for scenario simulations to understand the potential effects of a crisis and stress-test your plan. Ongoing communication helps prevent surprises and allows for quick adjustments when your goals or market conditions change.
Document adjustments and their cost-benefit rationale for future audits and to help keep the plan on track if you change advisors.
Tips and best practices
- Ask for a written plan with detailed goals and costs.
- Review the strategy at least quarterly.
- Prioritize transparency around all fees and conflicts of interest.
- Set rebalancing rules and automate contributions.
- Use reports and dashboards to monitor results.
- Consider international diversification to reduce domestic risk.
Conclusion
A financial advisor is a strategic partner in wealth management, providing assessment, planning, and ongoing support to help you make more effective financial decisions. A financial advisor can turn goals into action, optimize costs, and manage risk in volatile economic conditions. Choosing a qualified professional can bring clarity and discipline and help improve results over time.
Before hiring an advisor, review their credentials, track record, compensation model, and transparency. Start with a thorough financial assessment and clear goals, and revisit the plan regularly. If you wish, schedule a meeting with an advisor to get an initial plan and compare your options.
Frequently asked questions about financial advising
What is a financial advisor?
A financial advisor helps individuals and businesses organize their wealth, plan investments and retirement, and manage cash flow. They turn goals into practical strategies by considering risk, time horizon, and liquidity. The service includes an initial assessment, a financial plan, and ongoing support to adjust as economic or personal circumstances change.
How does the financial advising process work?
The process starts with gathering information about assets, liabilities, and income, setting goals, and assessing the client’s risk profile. The financial advisor recommends a strategy with asset allocations, targets, and a timeline. Next come implementation, monitoring, and periodic reviews. Simulations and reports track performance and help guide tactical adjustments as needed.
What’s the difference between financial planning and investment management?
Financial planning tends to focus on specific projects and planning, with clear deliverables and flat fees. Investment management typically includes ongoing investment management and execution, with fees charged as a percentage of assets under management (AUM). Financial planning focuses on assessment and recommendations; investment management also includes implementation and operational monitoring.
When should I use a financial advisor?
Consider financial advice when organizing your wealth, planning for retirement, preparing your estate, evaluating major decisions (such as buying a home or selling a business), or seeking a professional assessment. It can help with tax optimization or with organizing your finances before making significant investments.
How much does it cost to hire a financial advisor?
Costs vary. In Brazil, a flat fee for a project may range from R$2,000 to R$30,000, depending on complexity; AUM models typically charge 0.5% to 2% per year of assets; product commissions vary by institution. According to industry reports, investors typically pay an average of 1% per year for professional management, depending on the level of service.
What common problems can a financial advisor help solve?
A financial advisor can help reduce debt, build an emergency fund, improve asset allocation, plan for retirement, and prepare an estate plan. They can also identify hidden investment costs and put risk management policies in place to protect wealth from unexpected events.
What are the main benefits of hiring an advisor?
Benefits include greater investment discipline, tax optimization, lower risk through diversification, professional monitoring, and time savings. A financial advisor helps you make data-driven decisions, which can increase your chances of reaching your financial goals over time.
How do I put an advisor’s recommended plan into action?
Start by setting a contribution schedule, authorizing asset transfers in line with the plan, and setting up automatic rebalancing when possible. Establish KPIs and quarterly reviews. Document decisions and stay in regular contact with your financial advisor to make adjustments. Use integrated platforms to simplify implementation and monitoring.
Artigos Relacionados
 SEO Analyst: Roles and Responsibilities
 Financial Analyst: A Complete Guide to a Successful Career
 Math Teachers: Roles, Skills, and Challenges in Modern Education
 Digital Marketing Manager: The Complete Guide to Mastering the Role
 Investment Advisor: A Complete Guide to Building a Successful Career
 Logistics Director: A Complete Guide to the Role and Its Demands
